U.S. Homeowners: Protect Your Hurricane Roof Damage Claim in 72 Hours

If you see missing shingles, granule piles in the gutters, or damp insulation in the attic after a hurricane, assume the roof is compromised until a professional says otherwise. Stay off the roof, photograph every visible sign from the ground and inside the attic, and call both your insurer and a licensed roofer within the first day or two. Check your policy for a named-storm deductible, and if the roof needs emergency covering, ask about FEMA’s Operation Blue Roof before paying out of pocket for a tarp.
TL;DR:
- Even if a roof looks intact, wind uplift can loosen fasteners and lift shingles at edges and ridges, risking hidden structural damage.
- A significant portion of homeowner-flagged storm damage turns out to be cosmetic, so professional assessment and detailed estimates are crucial before claiming.
- Inspect from the ground with binoculars and check the attic only if safe, capturing timestamped photos to support your insurance claim and verify storm timing.
- Immediate actions within 72 hours, such as documenting damage and applying a professional tarp, can prevent further water intrusion and reduce overall repair costs.
- Major signs of damage include missing shingles, dents, daylight through the roof, or water stains, which require prompt professional evaluation rather than DIY fixes.
Table of Contents
- How Hurricanes Damage Roofs: The Four Mechanisms to Know
- Signs of Hurricane Roof Damage, Inside and Out
- How to Inspect Your Roof Safely After a Hurricane
- What to Do in the First 72 Hours After the Storm
- Filing an Insurance Claim for Hurricane Roof Damage
- When to Call a Professional Instead of Doing It Yourself
- What a Qualified Roofing Contractor Should Deliver
- What Homeowners Get Wrong After a Storm
- Get Emergency Roof Help From Top Florida Roofing
- Sources
- FAQ
How Hurricanes Damage Roofs: The Four Mechanisms to Know
Hurricane roof damage rarely comes from one cause. It’s usually a combination of four forces working against your roof at once, and understanding them helps you know where to look and why a roof that “looks fine” from the street can still be failing underneath.
- Wind uplift pulls at the edges, ridges, and corners first, since that’s where negative pressure is strongest. Fasteners loosen, shingle tabs lift, and metal edging peels back even when the field of the roof looks untouched.
- Wind-driven rain gets pushed sideways and even upward under shingles, tiles, and flashing, soaking the underlayment and deck long before you’d notice a ceiling stain.
- Debris and hail impact bruises or punctures the roofing material. A dent from a branch or hailstone can fracture the shingle mat without breaking the surface, which is why it’s easy to miss.
- Prolonged cyclic loading from sustained wind fatigues fasteners and seams over many hours, weakening connections that a shorter storm wouldn’t touch.
The Florida Disaster technical guidance on roofs points out that roof failures often start small and compound, especially once wind-driven rain finds a gap that uplift already created. Losing even one sheathing panel can raise interior damage risk by a factor of nine, according to The Roofing Brief’s analysis of hurricane roof damage, because it opens a direct path for water into the attic and living space below.
Signs of Hurricane Roof Damage, Inside and Out
Some damage announces itself. Most of it doesn’t. A roof can lose structural integrity while still looking intact from the driveway, which is exactly why insurers and adjusters check both the exterior and the attic before ruling on a claim.
Exterior signs to check from the ground:
- Missing, curled, or lifted shingles, especially along ridges and edges
- Granules collecting in gutters or at downspout outlets, a sign the shingle surface is wearing away
- Bent, dented, or missing flashing around chimneys, vents, and skylights
- Dented gutters or roof vents, which often confirm hail or windborne debris impact
- Visible daylight through the roof deck when viewed from inside the attic
- Standing debris, branches, or granule streaks that suggest impact points worth photographing closely
Interior and attic signs that matter just as much:
Water stains on the ceiling or upper walls, wet or matted insulation, soft or spongy sheathing underfoot, and a musty smell are all signals that moisture has already gotten in. Bubbling paint or a slightly sagging drywall patch usually means water has been sitting there for more than a few hours.

Pro Tip: Take one wide shot of the whole roof section for context, then a close-up of each damage point with something for scale, like a tape measure or a coin. Adjusters and contractors both work faster with photos that show scope and detail together.
Not every mark is a claim. According to Anvilfield’s storm damage field guide, a genuine hail hit fractures the shingle mat, while a surface scuff is purely cosmetic and won’t affect performance. Roughly 30 percent of what homeowners flag as storm damage during a self-inspection turns out to be cosmetic wear once a contractor tests it, which is one reason a written, line-item estimate from a licensed roofer matters more than a phone photo.
How to Inspect Your Roof Safely After a Hurricane
Never climb onto a wet, wind-damaged roof to check for problems yourself. Standing water, loose decking, and downed power lines make a post-storm roof one of the more dangerous places on a property, and most homeowner insurance doesn’t cover injuries from DIY roof inspections gone wrong.
Work through the inspection in this order instead:
- Ground level first. Walk the perimeter with binoculars and a camera. Scan eaves, ridges, valleys, and every flashing point around chimneys and vents.
- Gutters and downspouts. Look for granules, dents, and detached sections; these often confirm storm impact even when the roofing above looks fine.
- Attic last, and only if it’s safe to enter. Bring a flashlight and check the underside of the decking for water stains, wet insulation, or any spot where daylight shows through.
- Photograph everything with a timestamp. Date-stamped images are the backbone of a storm-damage roof inspection record.
- Pull an official storm report. The National Hurricane Center keeps historical storm tracks that help verify the exact date and intensity over your address, which strengthens your case with an adjuster.
Pro Tip: Save your NOAA storm report alongside your photos in the same folder. Adjusters move faster when the date of loss is already backed by an official record instead of your memory of when the storm hit.
What to Do in the First 72 Hours After the Storm
The first three days determine how smooth your insurance claim will be and how much additional damage your home sustains. Move through these steps in order, and don’t skip the documentation step to get to cleanup faster.
- Photograph and video everything before you touch it. Every damaged shingle, every water stain, every wet patch of attic insulation, dated and time-stamped.
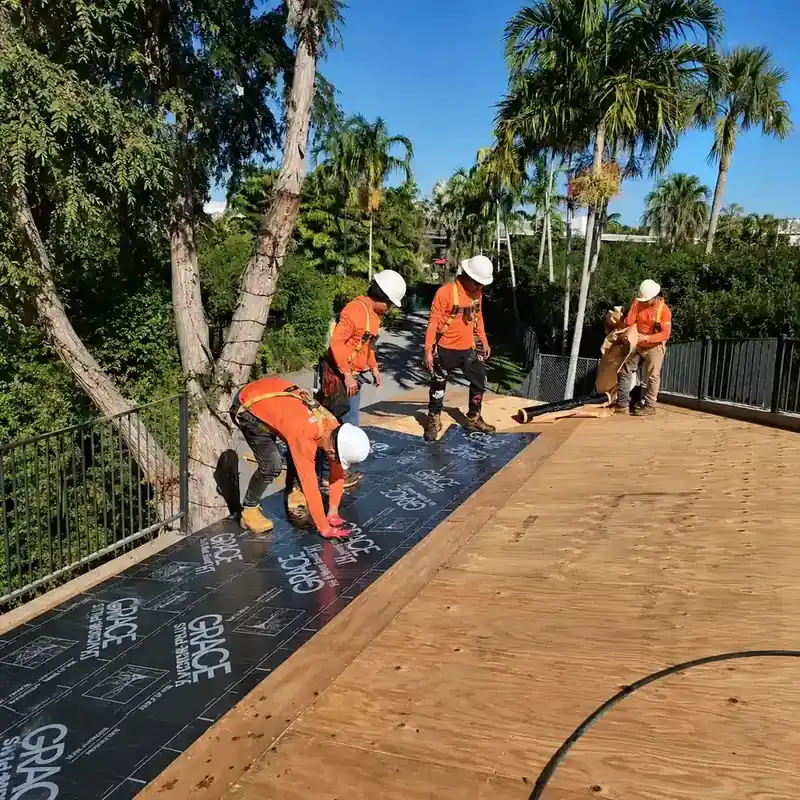
- Get a professional tarp installed rather than a DIY blue-tarp job if the damage is significant. A secured tarp over exposed decking stops rain intrusion during the wait for repairs.
- Clear debris from gutters and downspouts so water can drain instead of backing up under the roofline.
- Move valuables away from any area showing ceiling stains or sagging, since drywall failure can happen with little warning.
- Keep every receipt for tarps, temporary repairs, hotel stays if you’re displaced, and any emergency work. Insurers typically reimburse reasonable mitigation costs.
Acting within roughly 72 hours matters because wind-driven rain damage compounds fast. A wet attic left unaddressed for a week can mean replacing insulation and drywall that a same-day tarp would have saved.
Filing an Insurance Claim for Hurricane Roof Damage
Report the loss to your insurer as soon as you’ve documented it, ideally within the first day or two. Have your policy number, agent contact, and photo evidence ready before you call, since most insurers open a claim file on that first conversation.
Adjusters look for specific proof when they inspect a hurricane-damaged roof:
- Dents on soft metals like gutters, vents, and flashing, which confirm hail or debris impact even when shingles show less obvious signs
- A 10 by 10 foot test square used to count hail hits per area, a standard field method described in Anvilfield’s insurance restoration guide
- Attic moisture and decking condition, since a soaked sheathing panel usually means the deck needs replacing, not just the shingles
- Photo and video evidence tied to a verified storm date
One detail catches homeowners off guard almost every hurricane season: the named-storm or hurricane deductible. Unlike a standard flat-dollar deductible, this one is usually a percentage of your dwelling coverage, often somewhere between 1 and 10 percent depending on your policy and state. On a typical dwelling with a percentage hurricane deductible, homeowners can face thousands of dollars out of pocket before coverage kicks in, which is often much higher than a standard flat deductible.
It’s also worth knowing that standard homeowners policies cover wind damage but exclude flood damage entirely. If storm surge or rising water contributed to the loss, you’d need separate flood coverage through the National Flood Insurance Program or a private flood policy. Ready.gov’s claims guidance notes that adjusters typically make contact within 48 hours of a filed claim, and most insurers want supporting documentation submitted within 60 days, though some carriers extend that window after a major declared disaster. Ask your insurer directly about advance partial payments if repairs can’t wait for a final settlement.

When to Call a Professional Instead of Doing It Yourself
Some damage is a clear signal to stop inspecting and start calling. If you can see daylight through the attic decking, notice ceiling sagging, or count more than a handful of missing shingles or tiles, get a licensed roofer out immediately rather than attempting a patch yourself.
- A professional’s ladder and attic inspection catches deck damage that’s invisible from the ground
- Emergency tarping done by a licensed crew holds up far better in follow-up wind and rain than a DIY job
- FEMA’s Operation Blue Roof provides free temporary blue plastic sheeting to eligible homeowners after a declared disaster, installed by the U.S. Army Corps of Engineers at no cost, with an intended lifespan of about 30 days
- Eligibility requires a signed Right of Entry, and roofs with more than 50 percent structural damage or metal roofing may not qualify
- Keep every tarping and contractor receipt regardless of which route you take, since reimbursement often depends on paper trails
What a Qualified Roofing Contractor Should Deliver
A reputable contractor responding to hurricane damage should offer a free same-day inspection, a written line-item estimate, drone imagery for documentation, emergency tarping, and support navigating your insurance claim, backed by a real workmanship warranty. A qualified roofing contractor responding to hurricane damage should offer a free same-day inspection, a written line-item estimate, drone imagery for documentation, emergency tarping, support navigating insurance claims, and a workmanship warranty.
What Homeowners Get Wrong After a Storm
The biggest mistake isn’t missing damage. It’s waiting to document it, or letting a contractor who promises to “handle everything” skip the written estimate. Expect weeks, not days, for full claim resolution, and budget for your named-storm deductible up front.
— Rafael
Get Emergency Roof Help From Top Florida Roofing
If your roof took a hit this hurricane season, Top Florida Roofing gets a crew to your property fast, often within 2 hours, for 24/7 emergency response instead of making you wait days for a callback. That speed matters most in the first 72 hours, when a secured tarp is the difference between a repair job and a full interior rebuild.
A first visit typically includes a free same-day inspection with drone imagery to document every damage point, followed by a written, line-item estimate you can hand straight to your insurance adjuster. If tarping is needed, it’s handled the same visit, and the team can walk you through insurance claim assistance so the paperwork doesn’t fall entirely on you. For homes that need a documented inspection for a claim or HOA requirement, 4-point and wind mitigation inspections are available separately from full repair work. If your roof shows any of the signs covered above, request an inspection before the next storm system rolls through.
Sources
- Frequently Asked Questions about Operation Blue Roof
- Ready
- Understanding Roof Storm Damage: Causes, Signs, How to Inspect and Next Steps — GAF
- Hurricane damage to a roof: Signs, steps, and claims — The Roofing Brief
- Roof storm and hail damage assessment and insurance restoration field guide — Anvilfield
FAQ
Does Homeowners Insurance Cover Hurricane Roof Damage?
Most standard homeowners policies cover wind damage from a hurricane, but not flooding or storm surge, which requires separate flood coverage. Expect a percentage-based named-storm deductible to apply instead of your regular deductible, so check your policy declarations page for the exact figure.
How Long Do I Have to File a Roof Damage Claim After a Storm?
Report the loss to your insurer as soon as possible, ideally within a day or two of the storm. Ready.gov’s claims guidance notes adjusters typically make contact within 48 hours, and most insurers expect supporting documentation within 60 days or per your specific policy terms.
What Is the Test Square Method Adjusters Use?
Adjusters and contractors mark off a 10 by 10 foot section of roof and count hail or impact hits within it to gauge overall damage severity. This method, described in Anvilfield’s field guide, helps distinguish a legitimate storm claim from isolated cosmetic wear.
What Are the Signs My Roof Was Damaged by a Storm?
Look for missing or curled shingles, granules piling in gutters, dented flashing or vents, and attic signs like water stains or damp insulation, as outlined in GAF’s storm damage guide. If you spot any of these, document them with photos and schedule a professional inspection before assuming the damage is minor.