A Florida 4-point inspection documents four major home systems: the roof, electrical, plumbing and HVAC. An insurer may request it to evaluate a property before issuing or renewing coverage. It is not a full home inspection, a warranty or a promise that the application will be accepted.
Before booking, ask your insurance agent which form, inspector qualifications, report age and photographs the carrier requires. An inspection suitable for one insurer may not satisfy another.
What the four systems cover
Citizens' sample 4-point form illustrates the information an underwriter may expect. Your insurer may use a different form or require additional evidence.
- Roof: covering type, age or updates where known, observed condition, damage, leaks and an assessment of remaining useful life.
- Electrical: panel and wiring information, capacity and visible hazards. Panel access should be handled by a qualified professional, not the homeowner.
- Plumbing: piping information, visible connections, water heater details and evidence of leaks or deficiencies.
- HVAC: equipment information, heating and cooling operation, maintenance details and visible hazards or leakage.
The report records conditions for underwriting. It should identify deficiencies and limitations rather than guarantee how long each system will last.
Who can complete and sign the report?
The Citizens sample requires a verifiable Florida-licensed professional to complete, sign and date the report. Its examples include general, residential or building contractors, building code inspectors and home inspectors. Confirm your carrier's current requirements rather than treating that example list as acceptance by every insurer.
The form also states that a trade-specific licensed professional may sign only the section for that trade. Roof assessment and repair records may support the roofing portion, but do not replace the electrical, plumbing and HVAC evaluation.
Before hiring, request the professional's license information and confirm that the proposed scope covers the whole report if that is what your carrier needs. If separate trades are involved, ask the agent how the complete documentation must be assembled and signed.
Roof documentation and remaining useful life
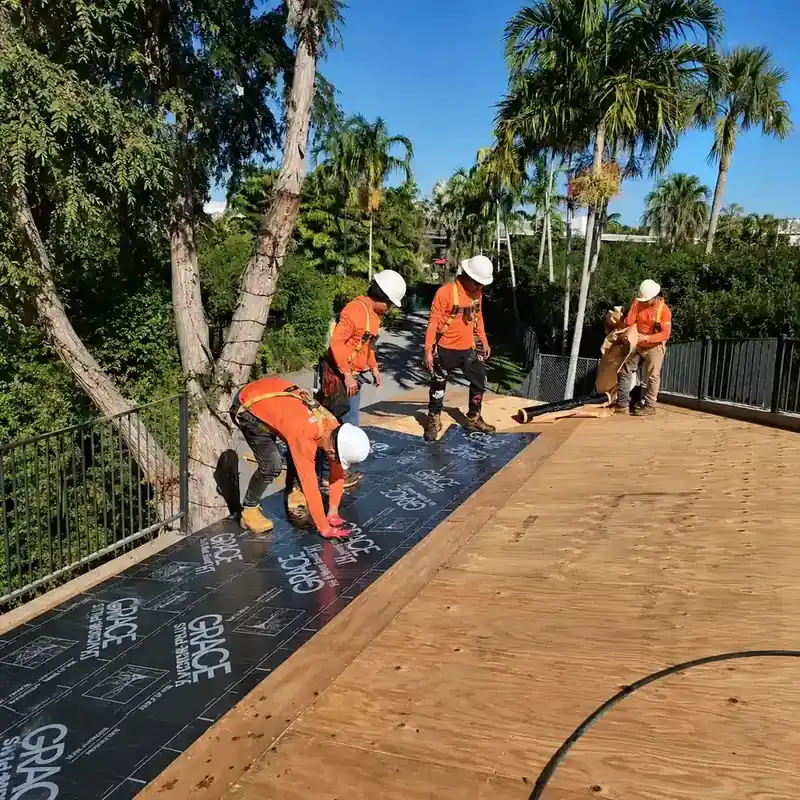
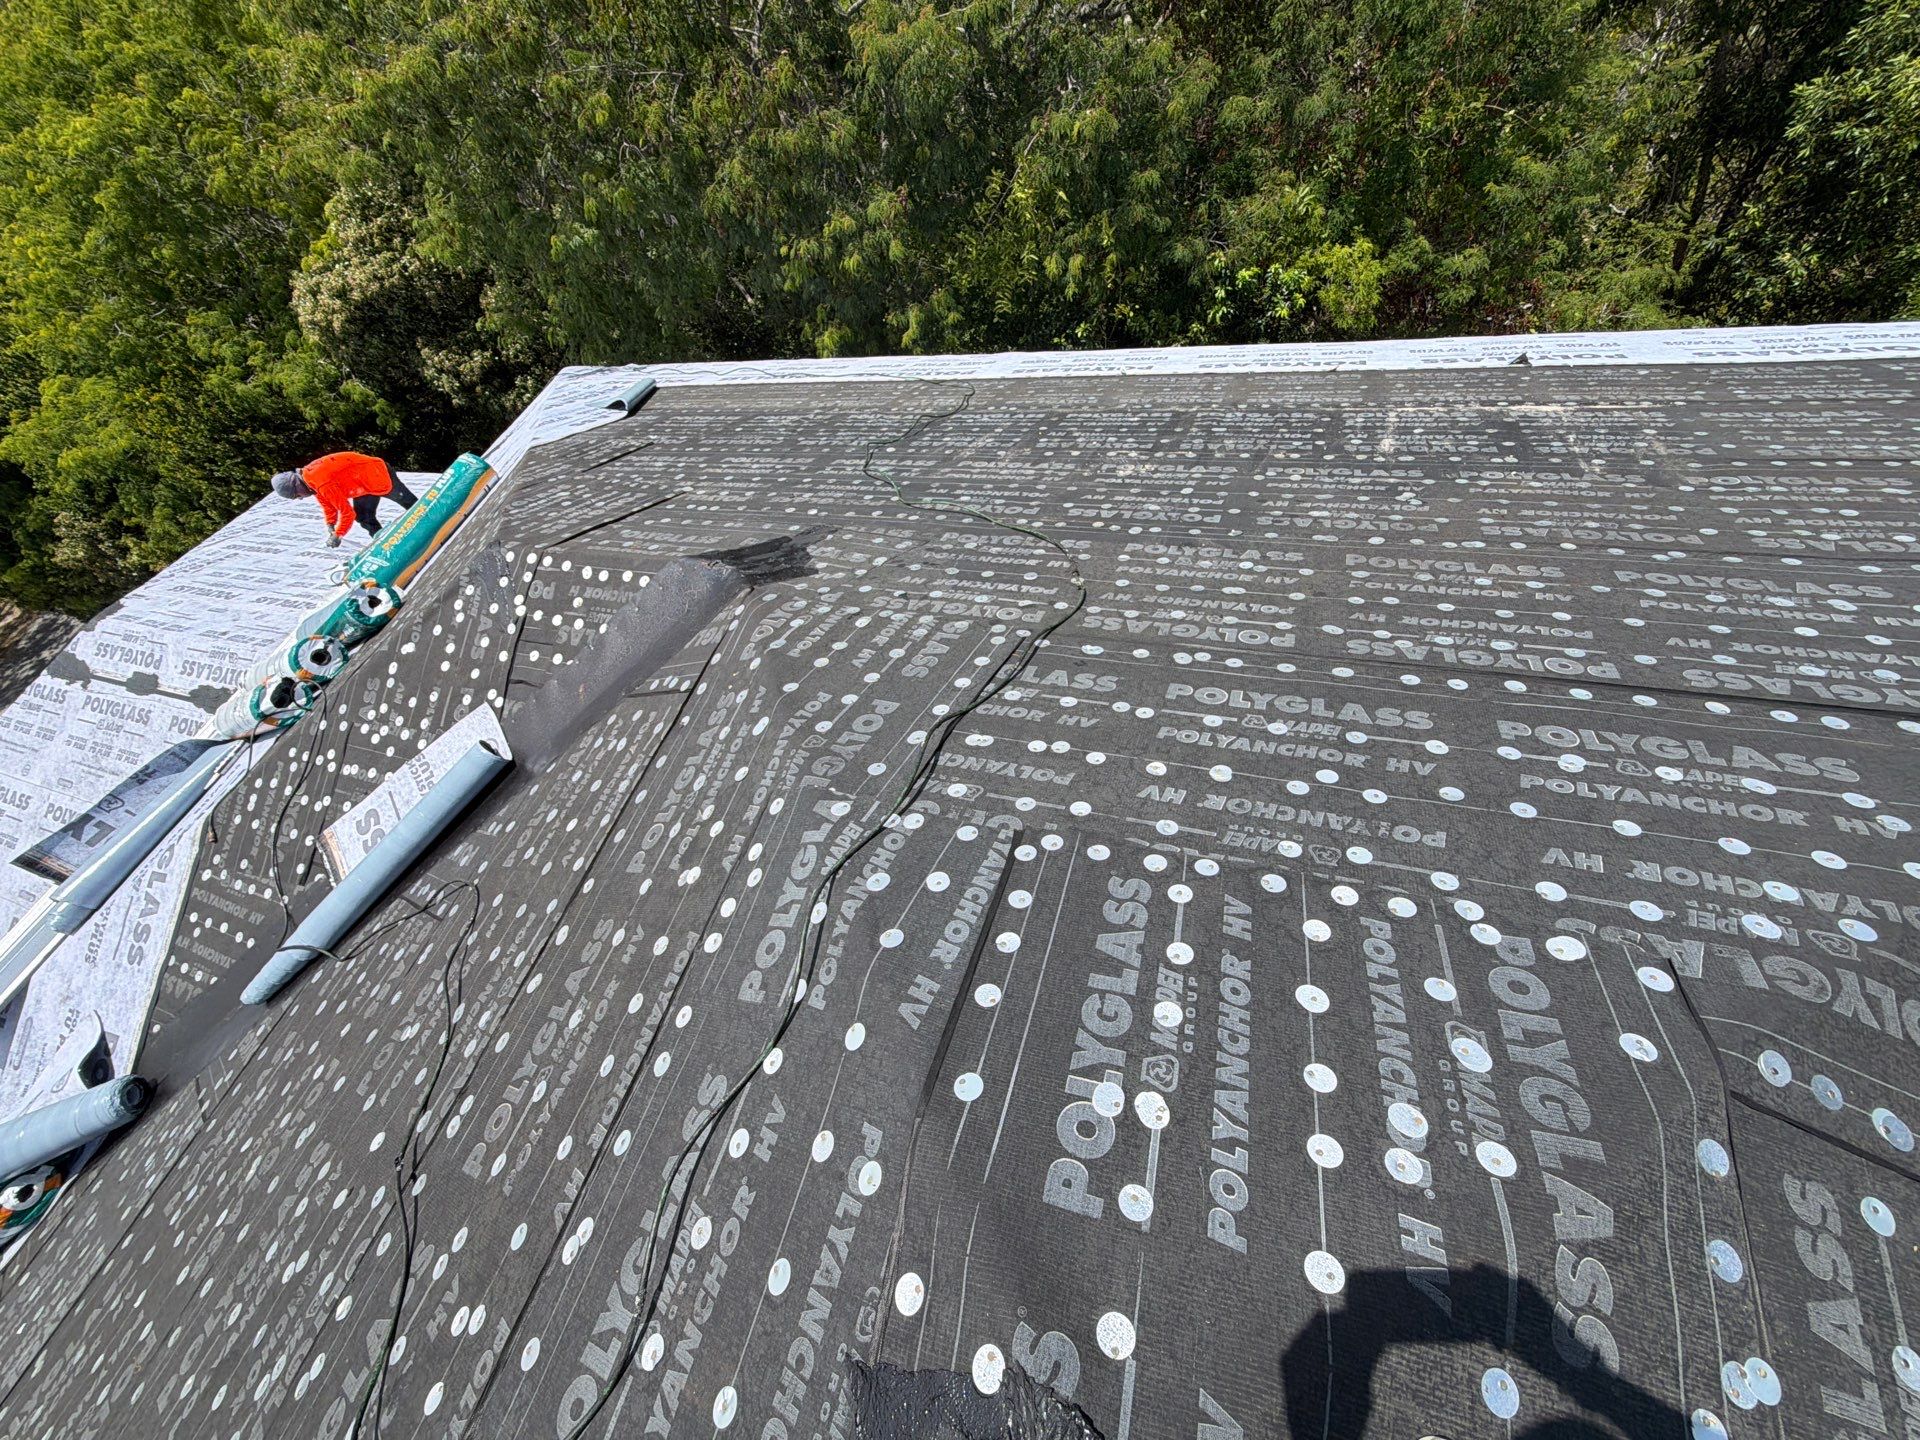
For the roof portion, have prior replacement permits, invoices and repair records available. Citizens' sample asks about remaining useful life, damage, deterioration and signs of leaks. It also requires photographs of every roof slope.
A roof's age is useful evidence, but does not alone establish its condition. Material, installation, repairs, exposure and observed defects also matter. Do not assume that all shingle, tile or metal roofs have the same underwriting age limit or that one remaining-life number satisfies every carrier.
A remaining-life opinion is an assessment, not a guarantee against future leaks. Ask the agent whether the insurer requires a specific roof form or accepts the roof portion of the requested 4-point report.
How to prepare for the visit
- Obtain the insurer's current form and requirements before scheduling.
- Confirm accepted signer qualifications and the maximum acceptable report age.
- Gather permits, invoices, maintenance records and documentation of prior corrections.
- Clear normal access to equipment and plumbing areas without opening electrical panels or creating unsafe access.
- Tell the inspector about known leaks or system problems rather than concealing them.
- Ask when the report will be delivered and how follow-up documentation is handled.
Citizens' sample photo requirements include each side of the dwelling, every roof slope, specified plumbing components, the main electrical panel and its required interior views, plus all reported hazards or deficiencies. HVAC equipment information is also part of the form. The professional should obtain any images requiring specialist access safely.
What to do about findings
Ask the agent or insurer what corrective evidence is needed. The required action may be a repair, additional assessment or replacement depending on the condition and underwriting rules. A recommendation from a contractor does not, by itself, establish the insurer's coverage decision.
Use appropriately licensed trades for repairs. Citizens' sample specifically requires separate documentation of aluminum-wiring remediation certified by a licensed electrician. Do not attempt electrical remediation or remove panel covers yourself to obtain photographs.
Keep dated invoices and before-and-after photos. Confirm whether the carrier requires reinspection or will accept the repair documents. Correcting a deficiency does not guarantee acceptance, a particular premium or payment of an unrelated claim.
Booking, cost and service scope
Request a written fee covering the inspection, report, photos and any return visit. Cost and duration vary with the property, provider and scope. A free roof assessment should not be assumed to include a complete four-system insurance report.
A 4-point inspection and a wind mitigation inspection answer different underwriting questions. If the insurer requests both, confirm that both scopes and forms are included rather than assuming one replaces the other.
Top Florida Roofing can discuss the roof concern and what documentation is available through its roof insurance inspection services. Before booking, confirm who will complete and sign any required full 4-point report and whether the insurer accepts that provider and scope. For a roof-only concern, start with a roof assessment.
Frequently asked questions
Does every Florida home need a 4-point inspection?
Do not assume a universal requirement for every property. The insurer's application and renewal rules determine when it requests a report. Confirm the current requirement with your agent.
Can a roofer sign the complete report?
A trade-specific roofing license should not be assumed sufficient for all four systems. Citizens' sample limits trade-specific sign-off to that professional's section. Confirm the accepted full-report signer with the carrier.
Does a roof inspection replace a 4-point inspection?
No. A roof assessment can provide useful roofing evidence, but the complete 4-point includes electrical, plumbing and HVAC information as well.
What does it mean to fail a 4-point inspection?
The report records conditions and hazards. People may call an adverse underwriting result a failure, but the insurer decides whether the documented findings meet its acceptance criteria.
How long is the report valid?
Acceptable report age varies by carrier and transaction. Ask before booking, especially when changing insurers or submitting a report prepared for an earlier application.
- Citizens Property Insurance Corporation: Sample 4-Point Inspection Form — systems, photo evidence and signer instructions. Obtain the carrier's current requirements before booking.
General insurance information only; confirm coverage and underwriting requirements with your agent or insurer.